No family researching this page wanted to find it, so let me be as useful as the moment allows: this is what Nebraska’s workers’ compensation system provides when a worker is killed on the job, who receives it, what it does not cover — and the second claim that too many grieving families never learn they have.
What the System Pays, and to Whom
Nebraska workers’ compensation death benefits are wage-replacement benefits paid to the worker’s dependents, computed from the deceased worker’s average weekly wage under Neb. Rev. Stat. §§ 48-122 and 48-122.01. The core percentages:
- A surviving spouse alone receives 66⅔ percent of the deceased’s average weekly wage, payable during widowhood or widowerhood.
- A spouse with children receives a base percentage — 60 percent where the child lives in the household, 55 percent otherwise — plus 15 percent for each child.
- Children with no surviving spouse: 66⅔ percent for one child, with 15 percent added for each additional child, shared among them.
- Actually dependent parents, siblings, grandparents or grandchildren may receive 25 percent where no closer dependents take.
All of it is subject to the statutory maximum and minimum weekly amounts, which adjust over time — and that ceiling matters, because for a high-earning worker the maximum can bind long before the percentages do. Two further rules families should know at the outset: benefits to a surviving spouse continue during widowhood, and upon remarriage the spouse receives two years of benefits in a single lump sum; and the wage on which everything is computed is a fact to be proven, not a number to be accepted — overtime, second rates and bonuses belong in it, and an understated average weekly wage silently discounts every check the family will ever receive.
Burial Expenses — and the Bills That Come First
The statute provides reasonable burial expenses up to $11,000, a cap that adjusts annually with the consumer price index (by no more than 2.75 percent per year), payable without deduction from the other compensation owed. Where the death followed a period of medical treatment, the reasonable medical and hospital expenses of the final injury or illness are the employer’s responsibility under the compensation framework as well — families should not be paying trauma-center bills out of a funeral budget while a compensable claim sits unfiled.
Two housekeeping points that spare families grief later: keep every funeral, transport and related receipt from the first day, because the burial benefit is paid against documented reasonable expenses; and route the funeral home to the claim rather than paying from savings where possible — families who quietly absorb costs the statute assigns to the employer rarely get around to recovering them.
A word about the practical gap between the funeral and the first check. Insurers do not always move at the speed of a family’s rent, and the weeks after a workplace death are exactly when a lowball “let’s wrap this up for the family’s sake” overture is most tempting and most damaging. A death claim is the longest-tailed obligation in the compensation system — potentially decades of weekly benefits to a young widow or widower with small children — and its settlement value should be computed against that full stream, discounted honestly, never against the pressure of the first missed mortgage payment. This is, bluntly, the moment to have someone on the family’s side of the table who can do that arithmetic.
The Second Claim: Comp Is Not the Whole Story
Here is the most important paragraph on this page. Workers’ compensation is the exclusive remedy against the employer — but it pays nothing for the human loss: no compensation for the companionship, society and comfort the family lost, nothing for what the worker experienced. Those damages live in a different claim: a wrongful death action against any third party whose negligence contributed to the death.
Workplace deaths are third-party cases more often than families are ever told:
- A motor-vehicle death on the job — the largest single category — is a claim against the at-fault driver and every layer of coverage behind them;
- A construction-site death may reach a general contractor, another subcontractor, or a property owner;
- A machine-related death may be a product liability claim against the manufacturer of equipment that lacked a guard or interlock;
- A death in a collapse, electrocution or fall may implicate engineers, maintenance firms, or premises owners.
The two claims proceed together, with an interaction — the comp carrier generally holds subrogation rights against the third-party recovery — that has to be managed, not discovered at settlement. The scale difference justifies the effort: I have handled both sides of this architecture, including an $800,000 recovery for a family in a Sarpy County custodial death case, and the third-party claim is routinely where the larger share of a family’s recovery lives. The wrongful death page covers that claim in full.
Deadlines, and Why Death Claims Cannot Wait for Grief to Finish
It feels obscene to talk about deadlines to a grieving family, so I will talk about evidence instead, because evidence is the real emergency.
The legal clocks are short enough on their own: Nebraska wrongful death actions carry a two-year limitations period, workers’ compensation has its own filing deadlines, and where a governmental entity may be responsible — a county road, a public employer, a state vehicle — written-notice requirements far shorter than any of those can extinguish a claim while the family is still sorting the estate. But the evidence clocks are shorter still. OSHA’s investigation, where one occurs, proceeds on its own schedule; the employer’s internal investigation begins immediately and serves the employer; machines get repaired, sites get rebuilt, vehicles get salvaged, and electronic data gets overwritten on retention cycles measured in days and weeks.
A preservation demand in the first days — to the employer, to equipment owners, to carriers — costs a family nothing and holds the record open. It is the single most valuable early act in a workplace death case, and it is the reason to make one phone call before the funeral week is out, however wrong that feels. Nothing about that call commits the family to litigation, to a lawyer, or to any posture toward the employer — it commits the evidence to still existing when the family is ready to decide. The estate mechanics matter too: the wrongful death action is brought by the personal representative for the family’s benefit, so opening the estate promptly is not paperwork — it is standing.
How Carriers Defend Death Claims — Recognize the Moves
Families assume a workplace death is the one claim an insurer would not fight. The opposite is closer to true: because a death claim is the longest and largest obligation in the system, it draws the most sophisticated resistance — delivered gently, on condolence letterhead. The recurring moves:
- The endless investigation. Acceptance is neither granted nor refused; it is “pending review” for months, while a family with a lost income waits. Delay is not neutral — it is pressure, and it is the environment in which bad early settlements get signed. A claim that will ultimately be owed does not become more owed by being slow-walked, and pushing acceptance onto a schedule is one of the first things representation changes.
- The dependency dispute. Who counts as a dependent, whether a separated spouse qualifies, whether a stepchild or a child born after the death takes — carriers litigate the family tree because every excluded dependent shrinks the percentages. These questions have answers, but they are answers a grieving family should not be negotiating alone.
- The understated wage. Every percentage on this page multiplies against the average weekly wage, and a computation that drops the overtime, the shift differential or the second job silently discounts decades of benefits. The family’s own records — pay stubs, tax returns, the last year’s schedule — are the audit, and running that audit is standard work, not suspicion.
- The scope argument. He deviated from the route; she was off the clock; the heart attack was personal, not occupational. Course-and-scope defenses arrive in nearly every contested death case and are met with evidence about what the work actually demanded that day.
- The global “kindness” offer. One check, offered early, framed as sparing the family a process — priced against nothing, because the wage audit, the dependency analysis and the third-party investigation have not happened yet. It is the single most expensive signature available to a grieving family, and declining it costs nothing but nerve.
None of this means the people involved are villains. It means the family’s side of the table needs the same preparation the other side brings by default.
How the Two Recoveries Fit Together
When a family pursues both the compensation death claim and a third-party wrongful death case, the two recoveries do not simply stack — they interact, and the interaction is where families lose money to inattention.
The carrier’s subrogation interest. The workers’ compensation carrier that pays death benefits generally acquires a right to be repaid out of the third-party recovery for what it has paid. That right is real, but it is not self-executing arithmetic: the amounts are verified rather than accepted, the carrier’s share is negotiated — carriers routinely compromise their liens, particularly where the third-party case carried litigation risk the carrier did not share — and attorney fees and expenses that produced the recovery figure into the allocation. A family that settles the third-party case without resolving the lien has not finished the case; it has postponed the hardest part.
The future-credit problem. Because comp death benefits stretch forward — potentially decades for a young surviving spouse — the carrier’s interest is not only in what it has paid but in what it would otherwise pay. How a third-party settlement is structured against those ongoing obligations determines whether the family’s weekly benefits continue, pause, or offset, and the structuring is a matter of deliberate negotiation, not default. Handled well, the family keeps the benefit stream and the lion’s share of the liability recovery; handled carelessly, the settlement quietly purchases the carrier’s future obligations at the family’s expense.
The allocation question. A wrongful death recovery belongs to the statutory beneficiaries and is distributed under court supervision, with minors’ shares protected — another reason the estate must be properly opened and represented. Where beneficiaries’ interests diverge, allocation deserves independent attention rather than an afterthought at the signing table.
None of this complexity is a reason to forgo either claim. It is the reason the two claims belong in one set of hands, coordinated from the beginning — the combined recovery, net to the family, is what I am retained to maximize, and the coordination is where much of that maximization actually happens.
Questions Families Actually Ask
“He was technically a contractor.” Labels are argued, realities decide. Misclassification is endemic in the industries that kill workers — construction and trucking above all — and a “1099 contractor” whose hours, tools and methods the company controlled may be an employee for compensation purposes. The label on the paycheck is the beginning of the analysis, never the end.
“They say it was his fault.” Workers’ compensation is no-fault — the death benefits described above do not depend on proving the employer did anything wrong, and are not defeated because the worker made a mistake. The third-party claim applies comparative fault, where an allocation fight is normal and winnable with evidence.
“We were not married.” Dependency, not ceremony, drives much of § 48-122.01 — children are covered regardless, and actually-dependent family members have defined shares. Unmarried partners occupy genuinely difficult ground in the comp framework, which makes the third-party claim — where the analysis differs — more important, not less.
“The company keeps calling with an offer.” Decline politely and get advice. An early settlement of a death claim prices decades of statutory benefits and an unexamined third-party case at the moment the family knows least. There is no version of that trade that favors the family.
I handle these cases across Nebraska and Iowa, and the consultation costs nothing — including a consultation whose only outcome is confirming the insurer is treating your family fairly.
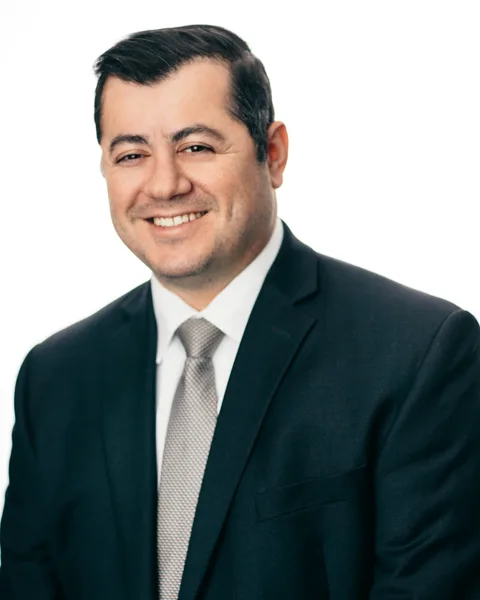
Your Attorney
Frank Younes
Every page on this site is written by Frank Younes, a Nebraska trial attorney with a published record of verdicts and settlements, selection to the National Trial Lawyers Top 100, and a practice that covers every county in Nebraska and Iowa. No case is handed to an associate — the lawyer you read here is the lawyer who works your case.
More about Frank → · Free consultation: (402) 378-9208
Frequently Asked Questions
What does a surviving spouse receive?
Under § 48-122.01, a spouse alone receives 66⅔ percent of the deceased worker’s average weekly wage during widowhood or widowerhood, subject to the statutory maximum. A spouse who remarries receives two years of benefits in a lump sum.
What do the children receive?
A spouse with children receives a base of 60 percent (55 if the child is not in their household) plus 15 percent per child; children with no surviving spouse receive 66⅔ percent for one child plus 15 percent for each additional child, shared among them — all subject to the weekly maximum.
How much is covered for the funeral?
Reasonable burial expenses up to $11,000, a cap adjusted annually for inflation by up to 2.75 percent per year, paid without deduction from other benefits. Medical expenses of the final injury are the employer’s responsibility under the compensation framework as well.
Can we also sue for wrongful death?
Not against the employer — comp is the exclusive remedy there — but against any negligent third party, yes: an at-fault driver, a general contractor or subcontractor, an equipment manufacturer, a property owner. That claim compensates the human loss comp ignores, and it is routinely the larger recovery.
The company says he was an independent contractor.
Treat that as an argument, not an answer. Misclassification is endemic in the deadliest industries, and a worker whose hours, tools and methods the company controlled may be an employee for compensation purposes regardless of the 1099.
What if the accident was partly his fault?
Death benefits are no-fault — they do not depend on employer wrongdoing and are not defeated by the worker’s own mistake. In the third-party claim, comparative fault applies and is fought with evidence.
How fast do we need to act?
Faster than the deadlines suggest. Wrongful death carries a two-year limit and governmental-entity claims far shorter notice windows — but the machines, sites, vehicles and electronic data disappear in days and weeks. A preservation demand in the first days is the most valuable early step, and it costs nothing.
Who actually brings these claims?
Comp death benefits are claimed by the dependents; the wrongful death action is brought by the estate’s personal representative for the family’s benefit — which is why opening the estate promptly is standing, not paperwork.
More in This Series
Other guides on Nebraska work injury claims.
Talk to Frank About Your Work Injury
Free, confidential consultation — in English or Spanish. No fee unless I win.
Call (402) 378-9208