One of the strangest things about a car crash is how differently the two halves of it move.
The vehicle part is fast. An adjuster calls within a day or two. Somebody looks at the car, a number gets quoted, and in under a week there's a check and a form to sign. For a lot of people it's the most efficient customer service they've had all year.
The injury part is slow, and it's supposed to be. You don't know on day four whether the stiff neck is a stiff neck or a disc. You don't know whether the headaches stop in two weeks or turn into six months of physical therapy. Nobody does — not you, not your doctor, and certainly not the adjuster.
So the paperwork for the fast half of your case shows up long before anybody understands the slow half. That's the whole problem in one sentence.
Know which claim you're settling
A property damage settlement is supposed to resolve one thing: the vehicle. Most of the time, that's exactly what it does, and there's nothing sinister about getting your car handled quickly. You need a car.
But the form in front of you is a legal document, and what it releases is a matter of what it says. Some forms are narrowly about the vehicle. Others use much broader language. The distance between those two things can be the difference between a car repair and every claim you will ever have from that crash.
So before you sign anything:
- Read the actual words. Look for language about "all claims," "bodily injury," "known and unknown," or "arising out of the accident." Those phrases are doing work.
- Notice what you're being asked to sign, and when. A form titled "release" is not the same animal as a repair authorization or a title transfer on a totaled vehicle.
- Don't sign it in the car in the lot. Take a photo of every page — front and back — and read it somewhere quiet.
- If you're hurt at all, ask someone first. A ten-minute phone call costs nothing. Undoing a signature can cost everything.
- Keep your own copy. Not a promise that they'll mail you one. A copy.
I'm not telling you the vehicle claim is a trap. I'm telling you it's a legal document that arrives at the exact moment you know the least about your own injuries, usually while you're stressed and without a car. That's a bad combination for careful reading, and careful reading is precisely what it needs.
The recorded statement that comes with it
Frequently the same call that handles your bumper also includes a friendly request: can I just get a quick recorded statement about how it happened? It sounds procedural. It is not. What you say in the first week — while you're minimizing, while you're saying "I'm fine, just sore," while you're guessing at speeds and distances — gets quoted back later with great precision.
"I'm fine" is what polite people say. It is also a sentence that turns up in a claims file eight months later when your shoulder still isn't right.
The money question underneath all of it
People sign early because they need money now. That's the honest reason, and it deserves an honest answer rather than a lecture. The bills don't wait for a settlement, and I've written about who pays for medical care while a Nebraska injury case is still open — there are usually more options than people realize. If an adjuster is already telling you your injuries can't be serious, you may also recognize the pattern I describe in why insurers still fight straightforward rear-end claims. And if you're trying to get a sense of what injury claims actually resolve for, I keep Nebraska settlement examples on the site.
Before you sign, call me
Reviewing a one-page form for somebody costs me a few minutes and can protect the entire value of their claim. I'd much rather have that call than the one that starts with "I already signed something, is that a problem?" As an Omaha car accident lawyer, I've built this practice on preparation and a genuine willingness to try a case — the work behind more than $23 million recovered for my clients, a $5.4 million top result, and the five-star reviews you can read yourself. My firm was voted Best of Omaha for personal injury law in 2025 and again in 2026.
If an insurance company has sent you paperwork after a crash, call me at (402) 378-9208 or reach out here before you sign it. The consultation is free, and there's no fee unless I win your case.
Frequently asked questions
- Does a property damage settlement also settle my injury claim?
- A property damage settlement is supposed to resolve one thing: the vehicle. Most of the time, that's exactly what it does. But the form in front of you is a legal document, and what it releases is a matter of what it says. Some forms are narrowly about the vehicle. Others use much broader language.
- What should I look for before signing a release after a car accident?
- Read the actual words. Look for language about "all claims," "bodily injury," "known and unknown," or "arising out of the accident." Those phrases are doing work. Notice what you are being asked to sign, and when — a form titled "release" is not the same animal as a repair authorization or a title transfer on a totaled vehicle.
- Should I give a recorded statement when the adjuster handles my vehicle claim?
- Frequently the same call that handles your bumper also includes a friendly request for a quick recorded statement. It sounds procedural. It is not. What you say in the first week — while you're minimizing, while you're guessing at speeds and distances — gets quoted back later with great precision.
Call Me Today at (402) 378-9208
The consultation is free, and there's no fee unless I win your case.
Call (402) 378-9208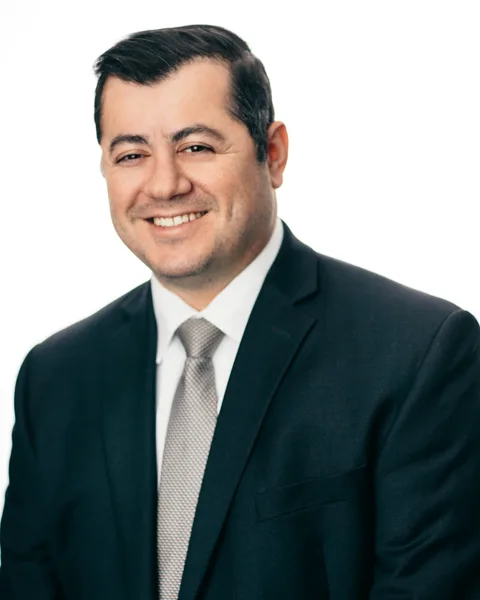
Your Attorney
Frank Younes
Every page on this site is written by Frank Younes, a Nebraska trial attorney with a published record of verdicts and settlements, selection to the National Trial Lawyers Top 100, and a practice that covers every county in Nebraska and Iowa. No case is handed to an associate — the lawyer you read here is the lawyer who works your case.
More about Frank → · Free consultation: (402) 378-9208